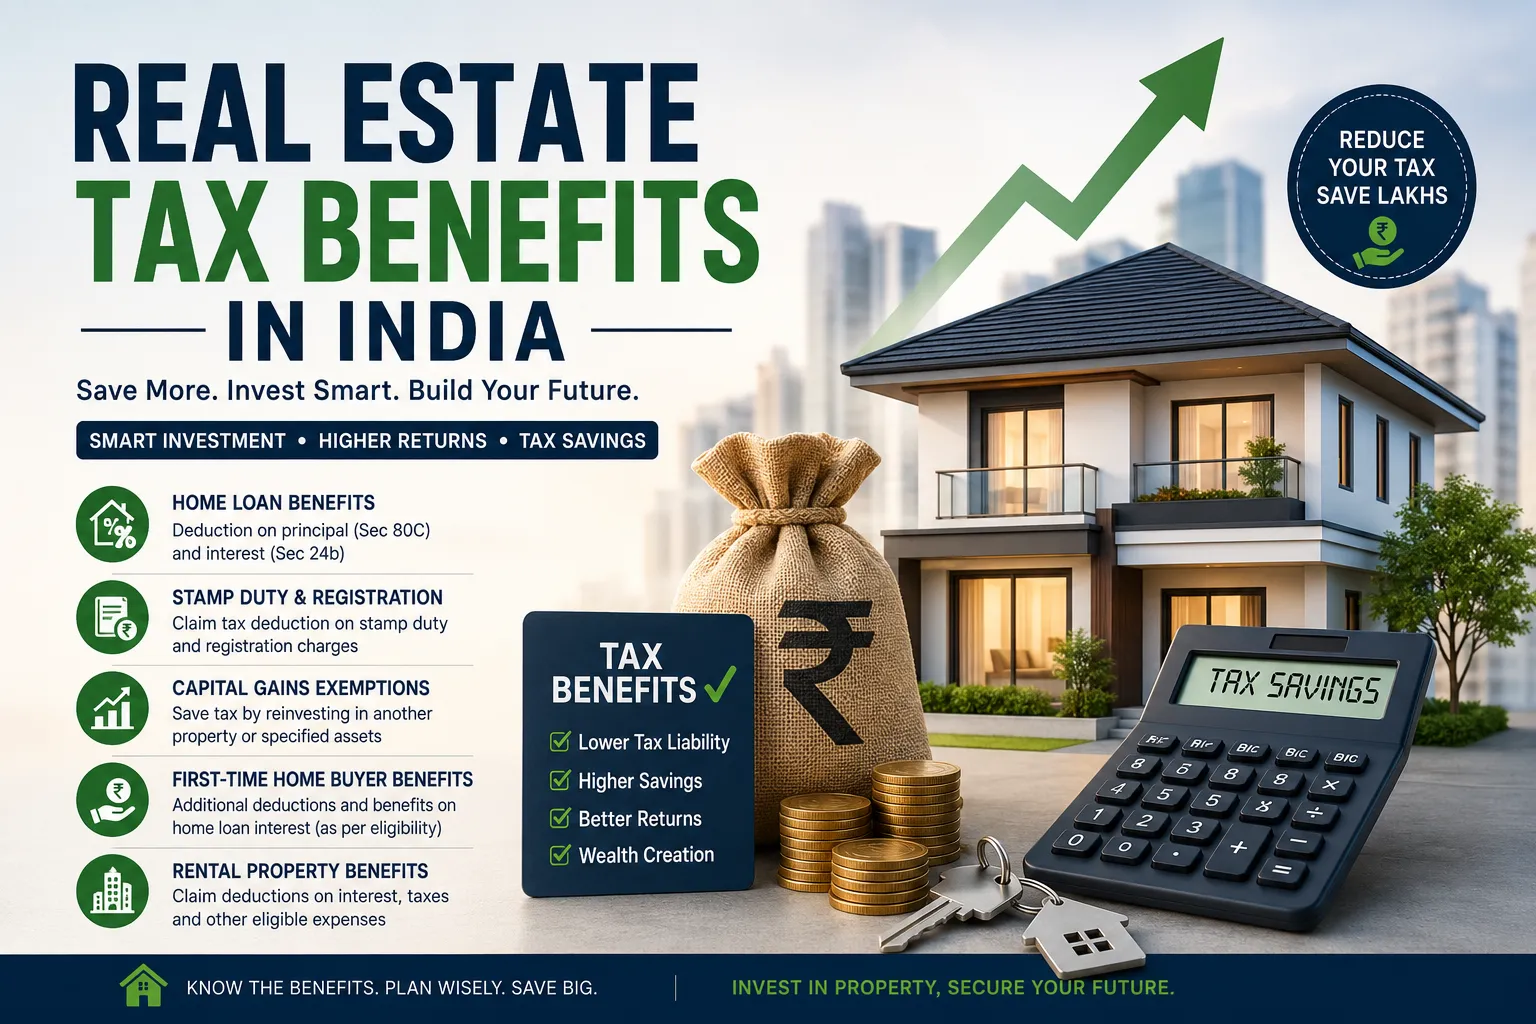
Real estate remains one of the most preferred investment options in India. Whether you are purchasing a residential property, investing in commercial real estate, or buying a plot for future construction, understanding the available tax benefits can significantly reduce your financial burden. The Indian government offers several tax deductions and exemptions to encourage property ownership and investment. By taking advantage of these provisions, buyers can save lakhs of rupees over the life of their investment.
If you are planning to invest in residential property or searching for plots through Khali Plot, understanding these tax benefits will help you make smarter financial decisions. This comprehensive guide explains every major tax benefit available under the Income Tax Act, along with important points every property investor should know.
Why Understanding Real Estate Tax Benefits is Important
Buying a property involves a substantial financial commitment. Apart from arranging the down payment and home loan, buyers also need to consider registration charges, stamp duty, maintenance expenses, and taxes.
Fortunately, the Income Tax Act provides various deductions that help reduce taxable income. Proper tax planning can:
- Lower your annual income tax liability
- Improve your return on investment
- Reduce the effective cost of owning property
- Encourage long-term wealth creation
- Make home loans more affordable
Knowing these benefits before investing enables buyers to structure their finances more efficiently.
Tax Benefits Available for Residential Property Buyers
Residential property buyers receive the maximum tax advantages in India. These benefits mainly relate to home loans, principal repayment, interest payments, and first-time home ownership.
Deduction on Home Loan Principal Under Section 80C
One of the biggest tax benefits available to homebuyers is under Section 80C of the Income Tax Act.
The repayment of the principal amount of a home loan qualifies for tax deduction up to ₹1.5 lakh per financial year.
This deduction also includes:
- Stamp duty
- Registration charges
- Certain property transfer expenses
However, the property should not be sold within five years from the date of possession. If sold earlier, the claimed deductions may become taxable.
Deduction on Home Loan Interest Under Section 24(b)
Interest paid on a home loan can also reduce your taxable income.
For self-occupied residential properties, buyers can claim deductions up to ₹2 lakh per year on interest paid.
If the property is rented out, the actual interest paid can generally be considered while computing income from house property, subject to applicable tax rules and overall loss adjustment limits.
This deduction is one of the largest tax-saving opportunities available to salaried individuals.
Additional Deduction for First-Time Home Buyers
To encourage affordable housing, the government has introduced additional deductions for eligible first-time home buyers through various provisions announced over the years.
Subject to applicable eligibility conditions and the relevant financial year's tax provisions, eligible buyers may receive additional deductions on home loan interest beyond Section 24(b).
Since these provisions may change with each Budget, buyers should verify the latest eligibility criteria before claiming benefits.
Tax Benefits on Joint Home Loans
Many families purchase properties jointly, especially spouses.
If both co-owners are:
- Legal owners
- Co-borrowers
- Contributing towards EMI payments
Each individual can separately claim:
- Up to ₹1.5 lakh under Section 80C
- Up to ₹2 lakh under Section 24(b)
This significantly increases the family's overall tax savings.
Tax Benefits for Under-Construction Properties
For under-construction properties, tax rules differ slightly.
Interest paid during construction cannot be claimed immediately.
Instead:
The accumulated pre-construction interest can be claimed in five equal annual installments after possession, along with the regular interest deduction.
This allows buyers to enjoy tax benefits even for properties that take time to complete.
Tax Benefits on Second Home
Many investors own more than one residential property.
Tax benefits are also available for second homes, although taxation depends on whether the property is self-occupied or rented.
Interest on the home loan may still qualify for deductions as per prevailing tax laws, making second-home investments financially attractive for many investors.
Tax Benefits for Affordable Housing
The Government of India has consistently promoted affordable housing through various schemes.
Affordable housing buyers may receive additional benefits depending on:
- Property value
- Loan sanction date
- Loan amount
- Carpet area
- Government notifications applicable during the purchase period
These incentives have encouraged many middle-income families to purchase their first homes.
Tax Benefits on Stamp Duty and Registration Charges
When purchasing a property, buyers pay:
- Stamp duty
- Registration charges
These expenses qualify for deduction under Section 80C within the overall limit of ₹1.5 lakh.
However, this deduction can generally be claimed only in the year these expenses are incurred.
Tax Benefits on Home Loan Processing Charges
In certain situations, processing fees paid for obtaining a home loan may be treated as part of borrowing costs and considered while computing eligible interest-related deductions, depending on applicable tax treatment.
Homebuyers should retain all documentation from their lender for accurate tax filing.
Tax Benefits for Rental Property Owners
Investing in rental properties offers multiple tax advantages.
Owners can claim deductions for:
- Home loan interest (subject to applicable rules)
- Municipal taxes paid
- Standard deduction on eligible rental income
- Certain repair-related allowances as permitted by law
Rental properties can therefore generate both monthly income and valuable tax savings.
Taxation of Capital Gains on Property
When selling a property, capital gains tax becomes applicable.
The tax depends on the holding period.
Short-Term Capital Gains
If a property is sold within the prescribed short-term holding period under current tax laws, gains are taxed according to the applicable provisions.
These gains are usually taxed differently from long-term gains.
Long-Term Capital Gains
Properties held beyond the prescribed long-term holding period receive long-term capital gains treatment under applicable tax laws.
Long-term gains may qualify for specific tax rates and exemptions, subject to prevailing legislation.
Capital Gains Tax Exemptions
Several provisions allow investors to save tax on capital gains.
Investment in Another Residential Property
Eligible taxpayers can claim exemption by investing capital gains in another residential property within the prescribed time limit.
Capital Gains Account Scheme
If immediate investment is not possible, eligible taxpayers may deposit capital gains into a Capital Gains Account Scheme before the due date for filing the return to preserve exemption eligibility, subject to applicable conditions.
Investment in Specified Bonds
Certain government-notified bonds also provide capital gains tax exemptions, provided investments are made within the prescribed timelines and limits.
Tax Benefits for Buying Plots
Many people believe only constructed homes provide tax advantages.
However, purchasing a plot also offers certain financial benefits.
What You Can Claim
- Deduction on stamp duty and registration charges under Section 80C, subject to overall limits and conditions.
- Capital gains exemptions may apply when reinvesting eligible gains into land or residential property as permitted under tax laws.
What You Cannot Claim Immediately
Buying only a plot without constructing a residential house generally does not qualify for home loan interest deductions available for completed residential properties.
If construction begins and the applicable conditions are fulfilled, buyers may later become eligible for relevant deductions.
For investors searching for residential plots through Khali Plot, understanding this distinction is important while planning finances.
Tax Benefits for Commercial Property
Commercial property investments are taxed differently from residential properties.
Business owners may be eligible for deductions related to:
- Loan interest
- Depreciation (where applicable)
- Maintenance expenses
- Municipal taxes
- Business-related operational costs
Commercial real estate can therefore provide both income generation and tax efficiency.
Home Loan Tax Benefits Under the Old and New Tax Regime
India currently offers two income tax regimes.
Old Tax Regime
The old regime generally allows taxpayers to claim several deductions related to home loans and property ownership, making it attractive for many homeowners.
New Tax Regime
The new regime provides lower tax rates but restricts many common deductions. Tax treatment for home loans depends on factors such as property type, rental status, and the provisions applicable for the relevant assessment year.
Before filing your return, compare both regimes to determine which offers greater overall tax savings.
Documents Required to Claim Property Tax Benefits
Maintain proper documentation to avoid issues during tax filing.
Important documents include:
- Home loan interest certificate
- Principal repayment certificate
- Loan sanction letter
- Property registration documents
- Stamp duty receipt
- Sale deed
- Possession certificate
- Completion certificate (if applicable)
- Municipal tax receipts
Keeping these records organized makes claiming deductions much easier.
Common Mistakes Property Buyers Should Avoid
Many buyers miss tax benefits because of simple errors.
Avoid these common mistakes:
- Not retaining loan documents
- Forgetting to claim stamp duty deductions
- Selling property before the mandatory holding period
- Claiming deductions without fulfilling eligibility conditions
- Ignoring joint ownership benefits
- Choosing the wrong tax regime without comparison
- Failing to report rental income correctly
- Missing deadlines for capital gains reinvestment
Consulting a qualified tax professional can help prevent costly mistakes.
Tax Planning Tips for Real Estate Investors
If you regularly invest in property, strategic planning can maximize returns.
Some useful tips include:
- Compare tax implications before purchasing.
- Plan home loans according to your repayment capacity.
- Evaluate whether joint ownership provides better tax savings.
- Maintain complete documentation.
- Understand capital gains before selling.
- Review changes announced in every Union Budget.
- Invest for the long term to maximize tax efficiency.
A well-planned property investment strategy can significantly improve overall returns.
Why Tax Knowledge Matters for Plot Buyers
Many investors purchase plots for future home construction or long-term appreciation. While immediate tax benefits on vacant land are limited compared to ready homes, proper planning can unlock advantages once construction begins or when the property is sold under eligible conditions.
Platforms like Khali Plot help buyers explore residential and investment plots across India. Before making a purchase, consider both the investment potential and the long-term tax implications so you can make an informed decision.
Real estate continues to be one of the most rewarding long-term investments in India, and the available tax benefits make property ownership even more attractive. From deductions on home loan principal and interest to exemptions on capital gains and stamp duty, understanding these provisions can help you save a substantial amount over time.
Whether you are buying your first home, investing in a second property, or planning to purchase a residential plot through Khali Plot, informed tax planning should be an essential part of your investment strategy. Since tax rules evolve with each financial year, always review the latest provisions or seek professional advice before making major property decisions.
By combining smart investment choices with effective tax planning, you can build long-term wealth while minimizing your tax burden.